
Mortgage Broker
Otago.
Last updated: October 2026
Mortgage broker in Otago, in short: Finch is an independent mortgage broker based in Te Atatu South, Auckland, working with clients across Otago by phone, video and secure online document upload. We compare 23 lenders, and for residential home loans our advice is free because the lender pays us when your loan settles.
What matters locally in Otago
- Large loans in the Queenstown Lakes
- Orchard and seasonal incomes
- Cribs and holiday homes
Why you can trust us with your mortgage
Home loans and refinancing across Otago
Otago runs from the Waitaki River to the Catlins and inland to the lakes and mountains of Queenstown and Wānaka. Dunedin is the main city, Central Otago is orchard and vineyard country, and the Queenstown Lakes district has some of the highest property prices in New Zealand.
That spread means very different borrowing in different towns: large, carefully structured loans in Wānaka and Arrowtown, seasonal orchard incomes in Cromwell, Alexandra and Roxburgh, and affordable older homes in Ōamaru, Balclutha and Milton. We compare 23 lenders by phone, video and secure online document upload.
What lenders look at in Otago
Large loans in the Queenstown Lakes
In Wānaka and Arrowtown, loans are bigger and debt-to-income limits bite sooner. Lender choice and loan structure make a real difference at these prices.
Orchard and seasonal incomes
Cherries, apricots and pinot noir drive Central Otago. Seasonal and self-employed incomes need presenting the way each lender assesses them.
Cribs and holiday homes
From Naseby to Wānaka, holiday homes are usually financed as investment-type loans, and lenders differ on counting short-stay income.
Older homes and heritage
Ōamaru's Victorian villas and the stone cottages of Clyde and Arrowtown are lendable, but insurance can cost more, so get a quote before you go unconditional.
Towns we cover in Otago
Each town page covers the local lending details that matter there, from property types to incomes and hazards.
City guides in Otago
Refinancing in Otago: five checks first
- Start four to six weeks before your fixed term ends. There's no break fee at the end of a fixed term, so that's the cleanest moment to switch or renegotiate.
- Know your break fee if you're mid-term. Your bank can quote it. We only recommend breaking a fixed rate when the saving clearly beats the cost.
- Check for a cashback clawback. If your current lender paid you a cash contribution in the last few years, some or all of it may have to be repaid if you leave.
- Count the switching costs. Expect legal fees for the new mortgage and sometimes a valuation. Some lenders contribute towards these.
- Compare your own bank's offer too. Sometimes the best result is a better deal from the lender you're already with, and we'll tell you if that's the case.
Run your numbers in the refinance savings calculator or read the NZ refinance guide.
Otago mortgage questions
See what refinancing could save you in Otago
Tell us when your fixed rate ends and roughly what you owe. We'll compare your bank's offer with other lenders and show you the numbers, including break fees and any cashback.
- ✓ Your bank's offer compared with the 23 lenders on our panel
- ✓ Break fees, legal costs and any cashback clawback worked out first
- ✓ We only recommend switching when the numbers work
- ✓ No fee on residential home loans: the lender pays us
Finch Mortgages Limited (FSP1011125) is an Authorised Body under Finsure New Zealand Limited's financial advice provider licence (FSP1005389). Disclosure statement
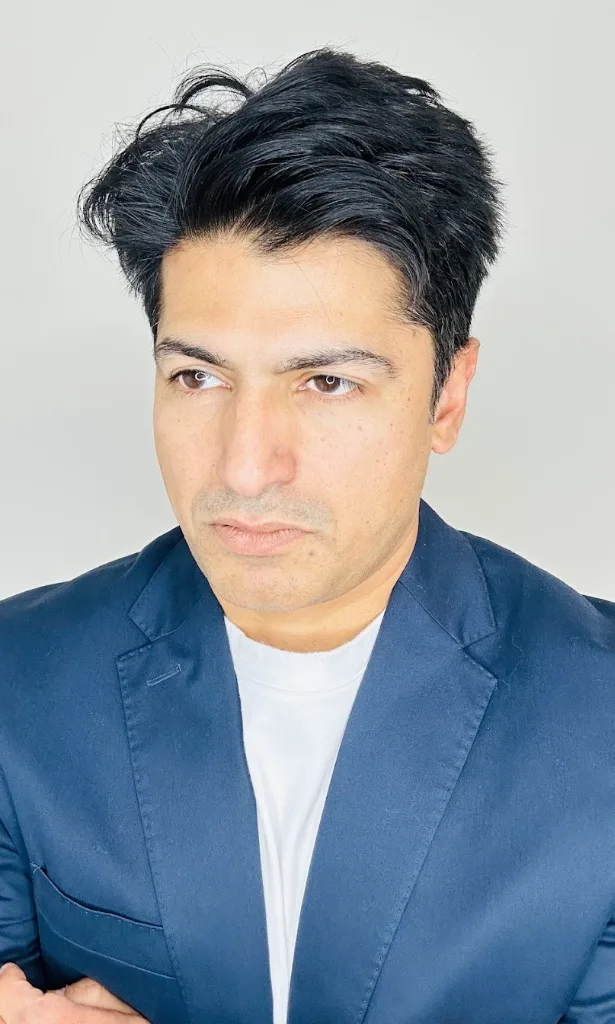
Your adviser
Mukhtar Kiyani
Director and Financial Adviser, with over 15 years of lending experience across ASB, Westpac and BNZ. Mukhtar works with Otago clients by phone and video, from first call to settlement.