
Mortgage Broker
Te Atatu.
Last updated: July 2026
Finch is based right here in Te Atatu South — a genuinely local independent NZ mortgage broker arranging home loans across Te Atatu Peninsula, Te Atatu South, Henderson, Massey, and the wider West Auckland area.
Why You Need an Independent Mortgage Broker in Te Atatu
If you go straight to your own bank, you only see that bank's rates and lending rules. As an independent mortgage broker covering Te Atatu & West Auckland, Finch compares your situation across our panel of 23 lenders. That includes banks such as ANZ, BNZ, SBS Bank, The Co-operative Bank and Heartland Bank, and specialist lenders such as Pepper Money, Avanti Finance, Liberty Financial and Basecorp Finance. Lenders change their rules and rates often, and the right choice can mean a quick approval at a good rate instead of a decline.
Te Atatu & West Auckland — Local Market Notes
West Auckland blends established post-war suburbs with fast-growing new-build corridors through Massey, Hobsonville Point, and Westgate. New builds across these areas typically qualify for the main-bank LVR exemption (10-15% deposit), while older weatherboard and cross-lease properties in Te Atatu and Glen Eden can attract additional lender scrutiny around insulation, Healthy Homes compliance, and title type. Knowing which lender treats each property type favourably is exactly what a local broker is for.
Suburbs & Areas We Cover Across Te Atatu & West Auckland
We arrange mortgages for clients across Te Atatu South, Te Atatu Peninsula, Henderson, Massey, Glendene, Kelston, New Lynn, Green Bay, Titirangi, Ranui, Swanson, Sunnyvale, Glen Eden, Royal Heights, West Harbour, Hobsonville, Westgate, and the wider West Auckland area.
Who Finch Helps in Te Atatu
Our typical Te Atatu clients include first home buyers across Henderson, Massey, and Te Atatu combining KiwiSaver and the Kāinga Ora First Home Loan; growing families upgrading within West Auckland; self-employed tradespeople and small business owners; investors targeting West Auckland rental yield; refinancers rolling off higher 2022-2023 fixed terms. We help salary and wage earners and self-employed people alike, including those trading through companies, look-through companies (LTCs), trusts and partnerships. We know which lenders are most likely to approve each kind of income.
Typical Te Atatu Property Price Bands (2026)
Te Atatu standalone homes typically $900k-$1.4m, Henderson and Massey $800k-$1.2m, West Auckland townhouses and new builds $650k-$900k, Titirangi and bush-fringe homes $1m-$1.6m+. These are indicative ranges only, not valuations. Your price range affects which deposit option suits you best, whether that's the First Home Loan, a family guarantee, a new build or a standard 20% deposit.
How the Finch Process Works for Te Atatu Buyers
- Free 15-minute discovery call — by phone or Zoom, no obligation.
- Document gathering — we send you a tailored checklist for Te Atatu.
- Lender match — we compare your situation across our lender panel and recommend the best one or two options.
- Pre-approval — typically issued within 5-10 working days for clean scenarios.
- House hunting in Te Atatu — bid at auction or negotiate by private treaty with certainty.
- Full approval & settlement — typically 4-6 weeks from accepted offer.
- Ongoing reviews — at every fixed-term roll-off and annually.
What Finch Costs (Spoiler: $0 to You)
For residential home loans, Finch charges you nothing. The lender pays us a commission when your loan settles, and we disclose it in writing before you act on our advice. New Zealand law requires financial advisers to put your interests first. Finch Mortgages (FSP1011125) is an Authorised Body under the Financial Advice Provider licence held by Finsure New Zealand Limited (FSP1005389). Read our disclosure statement.
First Home Buyer Support in Te Atatu
We help Te Atatu first home buyers make the most of every deposit option. That can include a KiwiSaver withdrawal (once you've been a member for three years), the Kāinga Ora First Home Loan (from a 5% deposit, through participating lenders), a family guarantee, or the new-build exemption under the Reserve Bank's LVR rules. Used together, these often stretch a deposit further than people expect. Read the full NZ first home buyer guide.
Refinance & Restructure for Te Atatu Homeowners
If your fixed term ends in the next 60 days, it's a good time to check whether your bank's renewal offer is competitive. Some lenders offer cashback when you switch, but it usually comes with conditions, and leaving early can mean break fees or repaying an earlier cashback. We work out the full cost before recommending any move. Use our refinance savings calculator for a quick estimate.
Common Questions We Hear
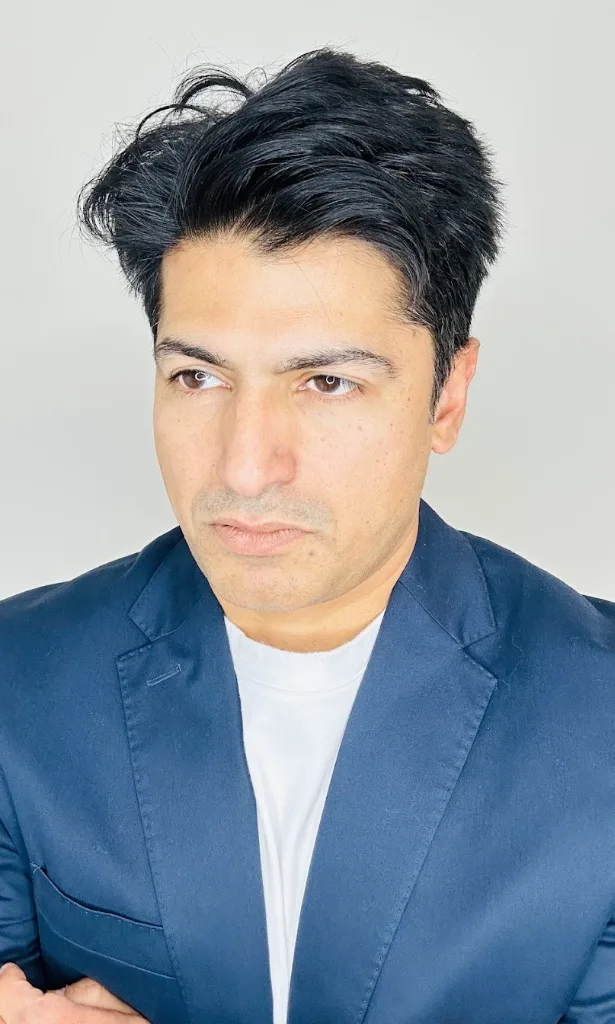
Written by Mukhtar Kiyani
Director & Financial Adviser · FSP1011206 | FSPR FSP1011125
Mukhtar has 15+ years of financial advisory experience across NZ mortgage lending, investment structuring, and first home buyer guidance. He founded Finch Mortgages with a mission to make expert, transparent mortgage advice accessible to every Kiwi. Based in Auckland, advising clients nationwide. View Profile →
Related NZ mortgage resources
Ready to talk to a
Te Atatu mortgage broker?
Book a free 15-minute consultation. No obligation, no cost — just honest NZ-specific advice.
Talk to a mortgage broker in Te Atatu
Tell us where you're at — buying, refinancing or just working out what you can borrow — and we'll come back with the lenders most likely to approve you.
Call 027 343 3293 now- ✓ We compare 20+ NZ banks and non-bank lenders
- ✓ The lender pays us — our advice costs you nothing
- ✓ Registered financial adviser (FSP1011206)
- ✓ Same-day reply on weekdays