
Mortgage Broker
Drury.
Refinancing, first homes and home loans for Drury, Auranga, Karaka, Rāmarama and Paerātā, compared across 23 lenders by phone, video or email.
Last updated: November 2026
Mortgage broker in Drury, in short: we compare 23 lenders for Drury buyers and homeowners by phone and video, with no fee on residential home loans.
What shapes lending in Drury
- New subdivisions and new builds
- Lifestyle blocks and rural-residential land
- Commuting from Drury
Buying and refinancing in Drury
Drury was a village at a motorway off-ramp. It's now one of Auckland's main growth areas, with thousands of homes planned or under way, new stations on the rail line to Pukekohe in the plans, and the motorway being widened. Karaka's lifestyle blocks and horse studs are next door.
Most Drury purchases are house-and-land packages or turnkey builds. The contract is signed a long time before the house is finished, and the loan is confirmed at the end. A lot can change in a year. We set up the approval with the build timeline in mind, and tell you what to avoid doing with your finances until you've settled.
What lenders look at in Drury
The local details most likely to decide which lender says yes.
New subdivisions and new builds
New housing is going up at Auranga and the other new neighbourhoods around Drury. New builds are exempt from the Reserve Bank's LVR restrictions, so some lenders accept a smaller deposit, but the bank values the home at completion.
Lifestyle blocks and rural-residential land
Plenty of Drury buyers are looking at land around Karaka, Rāmarama and Ararimu. Lenders treat a block as residential only up to a set land area and use, and look harder at farm income, tank water and septic systems, so the right lender matters.
Commuting from Drury
Many Drury households commute to Manukau and the city on the Southern Motorway. Lenders assess the whole household budget, travel costs included, rather than pricing the commute itself.
Terraces and townhouses
New Drury neighbourhoods include a large share of terraces and duplexes. Check whether the title is freehold or a unit title, because body corporate or residents' society levies count as a cost when lenders work out what you can borrow.
Refinancing your Drury home
- If you built or bought new, the end of your first fixed term is often the best moment to compare lenders, because your home's value and your equity may have changed.
- Refinancing a lifestyle block means a fresh valuation, and the new lender's own land-size and water rules apply, so we check those before you apply.
The usual checks still apply: your fixed-term end date, any break fee and any cashback clawback. The NZ refinance guide walks through them, and the refinance savings calculator shows what a lower rate is worth.
Drury at a glance
Before you buy or switch: local checks
Mortgage questions from Drury
See what refinancing could save you in Drury
Tell us when your fixed rate ends and roughly what you owe. We'll compare your bank's offer with other lenders and show you the numbers, including break fees and any cashback.
- ✓ Your bank's offer compared with the 23 lenders on our panel
- ✓ Break fees, legal costs and any cashback clawback worked out first
- ✓ We only recommend switching when the numbers work
- ✓ No fee on residential home loans: the lender pays us
Finch Mortgages Limited (FSP1011125) is an Authorised Body under Finsure New Zealand Limited's financial advice provider licence (FSP1005389). Disclosure statement
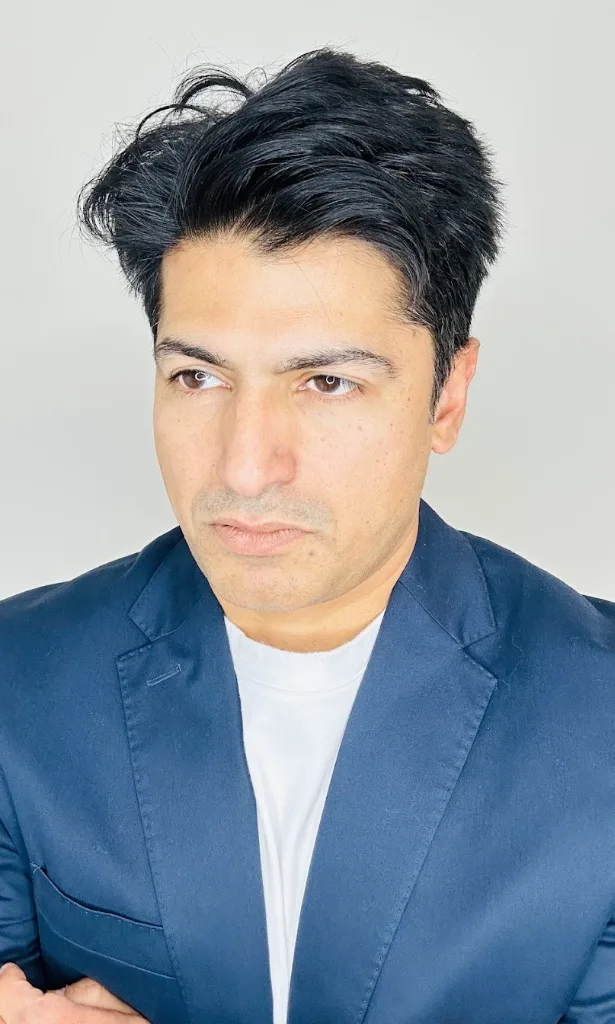
Your adviser
Mukhtar Kiyani
Director and Financial Adviser, with over 15 years of lending experience across ASB, Westpac and BNZ. Mukhtar works with Drury clients by phone and video, from first call to settlement.