
Mortgage Broker
Ōtāhuhu.
Refinancing, first homes and home loans for Ōtāhuhu, Middlemore, Māngere East, Favona and Mt Richmond, compared across 23 lenders by phone, video or email.
Last updated: November 2026
Mortgage broker in Ōtāhuhu, in short: we compare 23 lenders for Ōtāhuhu buyers and homeowners by phone and video, with no fee on residential home loans.
What shapes lending in Ōtāhuhu
- Older homes, repairs and upgrades
- Terraces and townhouses
- Commuting from Ōtāhuhu
Buying and refinancing in Ōtāhuhu
Ōtāhuhu sits on the narrowest part of the Auckland isthmus, between the Tāmaki River and the Manukau Harbour. It has one of the city's busiest bus and train interchanges, a long main street, and industry on three sides.
The housing is older than in neighbouring suburbs, and the sections are larger. That appeals to buyers planning to add a dwelling. Building at the back is construction lending, with consented plans and a fixed-price contract, not a simple top-up. For buyers who just want a home, older houses mean a building report is money well spent.
What lenders look at in Ōtāhuhu
The local details most likely to decide which lender says yes.
Older homes, repairs and upgrades
Ōtāhuhu has streets of villas and bungalows, older than most of South Auckland's housing. A mortgage top-up is usually a cheaper way to fund insulation, heating or repairs than personal lending, if you repay it over a short term.
Terraces and townhouses
Terraces are being built on larger sites near the station and town centre. Check whether the title is freehold or a unit title, because body corporate or residents' society levies count as a cost when lenders work out what you can borrow.
Commuting from Ōtāhuhu
Many Ōtāhuhu households commute to the city or Manukau by train from the Ōtāhuhu interchange. Lenders assess the whole household budget, travel costs included, rather than pricing the commute itself.
Rental investors
Older houses on big sections draw investors and small developers. Investors are tested against the Reserve Bank's debt-to-income settings, and lenders count only part of the rent.
Refinancing your Ōtāhuhu home
- A refinance with a top-up can fund insulation, heating or a re-roof at a mortgage rate rather than through a higher-cost loan.
- If you bought a new terrace off the plans, your first refix is a good time to check its value and whether you now qualify for standard pricing.
The usual checks still apply: your fixed-term end date, any break fee and any cashback clawback. The NZ refinance guide walks through them, and the refinance savings calculator shows what a lower rate is worth.
Ōtāhuhu at a glance
Before you buy or switch: local checks
Mortgage questions from Ōtāhuhu
See what refinancing could save you in Ōtāhuhu
Tell us when your fixed rate ends and roughly what you owe. We'll compare your bank's offer with other lenders and show you the numbers, including break fees and any cashback.
- ✓ Your bank's offer compared with the 23 lenders on our panel
- ✓ Break fees, legal costs and any cashback clawback worked out first
- ✓ We only recommend switching when the numbers work
- ✓ No fee on residential home loans: the lender pays us
Finch Mortgages Limited (FSP1011125) is an Authorised Body under Finsure New Zealand Limited's financial advice provider licence (FSP1005389). Disclosure statement
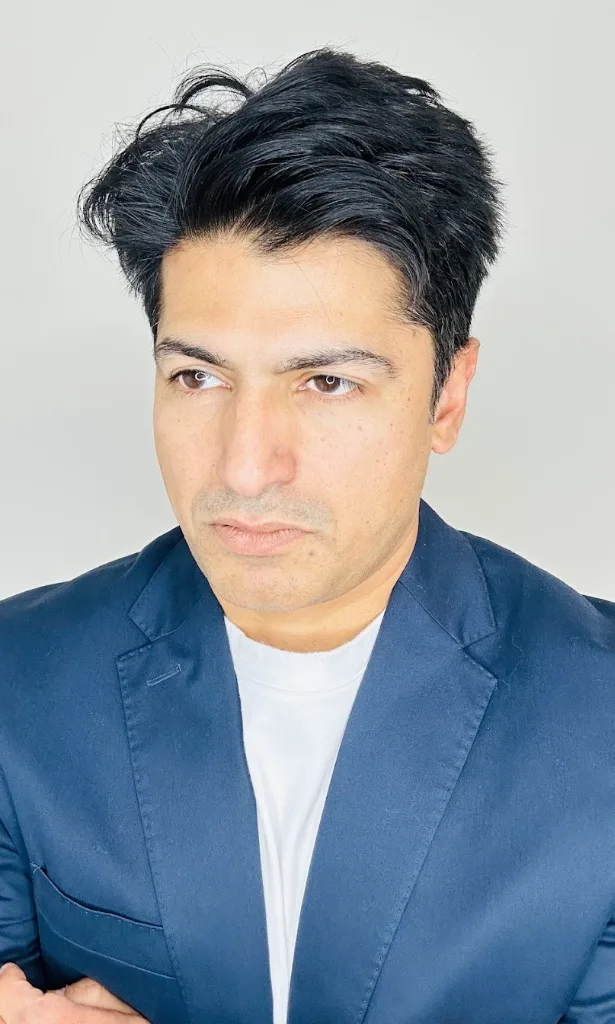
Your adviser
Mukhtar Kiyani
Director and Financial Adviser, with over 15 years of lending experience across ASB, Westpac and BNZ. Mukhtar works with Ōtāhuhu clients by phone and video, from first call to settlement.