Construction Loans NZ to
Build From the Ground Up.
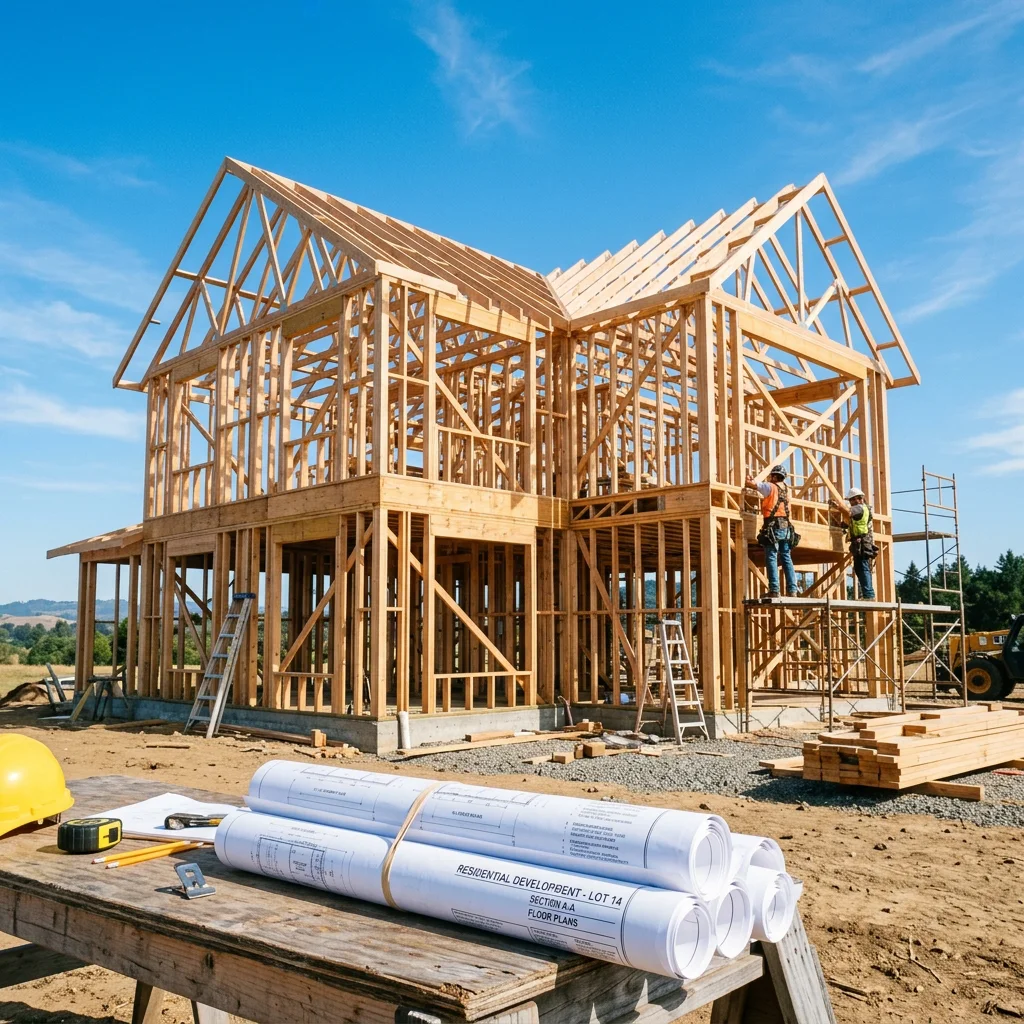
Construction finance requires careful timing and cash flow management. We specialise in turnkey builds, progress payments, and multi-unit development funding.
What we do for
construction projects.
Turnkey Builds
Lending solutions for off-the-plan or house & land packages purchased from a builder.
Progress Payments
We manage the complicated drawdown schedule as each stage of your build completes.
Minimal Deposits
New builds are exempt from normal LVR rules, meaning lower deposits are possible.
Cost Overrun Buffers
We build in contingencies to protect you against unexpected material or labour costs.
Land Bank Loans
Finance to purchase a section now and keep your options open for building later.
Development Finance
Solutions for multi-unit dwellings, subdivisions, and larger developer projects.
How it works
step by step.
A first conversation
We talk through the land, the build, your budget and your income. Free, and no obligation.
Check the numbers
We test the whole project: land, build, site works, fees and a contingency. Then we tell you which lenders will fund it and what deposit they'd want.
Approval
We submit the application with your plans, contract and valuation. The lender approves the total and the stages.
Progress payments
As each stage is finished, the builder invoices, the lender checks the work and releases the payment. We manage the drawdown requests.
Completion
Once the code compliance certificate is issued, the loan converts to a standard home loan and we set its long-term structure.
How construction finance works
A construction loan isn't paid out in one go. The lender releases money in stages as the build progresses, and you pay interest only on what's been drawn. That keeps costs down during the build. It also means more paperwork than a standard home loan.
Turnkey or progress payments
With a turnkey contract you pay a deposit and settle when the house is finished, so the builder carries the cost of construction. With a progress-payment build you fund each stage. Turnkey is simpler and you pay no interest until the end. A staged build can cost less and gives you more control. Compare them in turnkey home loans and how progress payments work.
What lenders want before they'll approve
A fixed-price contract with a licensed builder, building consent or consented plans, a valuation of the finished home, and a contingency for overruns. Lenders are cautious about labour-only contracts and owner-managed builds. If you already own the section, your equity in it counts towards your contribution. Buying the land first is covered in getting a loan for land.
Deposits on new builds
New builds are exempt from the Reserve Bank's loan-to-value restrictions, so lenders have more room to accept a deposit under 20%. Each sets its own limit, and low-deposit pricing may apply.
What goes wrong
Delays and cost increases, mostly. Builds take longer than the brochure says, and a pre-approval can expire before the house is finished, so the lender reassesses you at the end. Keep your job and debts steady while you build. Site costs on sloping or poor ground are the most common budget blowout, so get a geotechnical report early.
Renovating instead of building? Large renovations are funded the same way. See funding a renovation. For residential home loans our advice costs you nothing. The lender pays us when the loan settles, and we disclose that in writing.
Related NZ construction resources
Common Questions
Ready to start
your build?
Book a free consultation with a Finch mortgage adviser today. No obligation, no cost, just honest advice.
Building or renovating?
Tell us what you're buying and we'll come back with the lenders most likely to say yes — and at what rate.
Call 027 343 3293 now- ✓ We compare 23 NZ banks and non-bank lenders
- ✓ The lender pays us — our advice costs you nothing
- ✓ Registered financial adviser (FSP1011206)
- ✓ Same-day reply on weekdays