
Mortgage Broker
Epsom.
Refinancing, first homes and home loans for Epsom, Greenlane, Newmarket, One Tree Hill and Royal Oak, compared across 23 lenders by phone, video or email.
Last updated: November 2026
Mortgage broker in Epsom, in short: we compare 23 lenders for Epsom buyers and homeowners by phone and video, with no fee on residential home loans.
What shapes lending in Epsom
- Cross-lease titles
- Adding a second dwelling
- Older homes, repairs and upgrades
Buying and refinancing in Epsom
Epsom sits between Maungawhau and Maungakiekie, and much of it falls inside the zones for Auckland Grammar and Epsom Girls Grammar. That keeps demand steady, and it means families often stretch to buy here.
Stretching is where we come in. Larger loans run into the Reserve Bank's debt-to-income limits sooner, and lenders differ on how they count bonuses, commission and business income. A well-chosen lender can add a meaningful amount to what you can borrow. For units, check the cross-lease plan matches what's built.
What lenders look at in Epsom
The local details most likely to decide which lender says yes.
Cross-lease titles
Epsom has many cross-leased units and townhouses, built when large sections were divided. Lenders accept cross-leases, but alterations that don't match the flats plan on the title can hold up a purchase or refinance until they're fixed.
Adding a second dwelling
Epsom's big sections have been steadily subdivided, and plenty of owners still look at adding a dwelling. Building at the back is construction lending, paid out in stages, and lenders want consented plans and a fixed-price contract first.
Older homes, repairs and upgrades
Large early-twentieth-century homes are typical of Epsom's older streets. A mortgage top-up is usually a cheaper way to fund insulation, heating or repairs than personal lending, if you repay it over a short term.
Rental investors
Units close to Newmarket and Greenlane are popular as rentals. Investors are tested against the Reserve Bank's debt-to-income settings, and lenders count only part of the rent.
Refinancing your Epsom home
- A new lender's lawyer rechecks the cross-lease when you refinance, so sort out any alterations that aren't on the flats plan before you start.
- If you plan to build a second dwelling, refinance to a lender that does construction lending well before you need the first progress payment.
The usual checks still apply: your fixed-term end date, any break fee and any cashback clawback. The NZ refinance guide walks through them, and the refinance savings calculator shows what a lower rate is worth.
Epsom at a glance
Before you buy or switch: local checks
Mortgage questions from Epsom
See what refinancing could save you in Epsom
Tell us when your fixed rate ends and roughly what you owe. We'll compare your bank's offer with other lenders and show you the numbers, including break fees and any cashback.
- ✓ Your bank's offer compared with the 23 lenders on our panel
- ✓ Break fees, legal costs and any cashback clawback worked out first
- ✓ We only recommend switching when the numbers work
- ✓ No fee on residential home loans: the lender pays us
Finch Mortgages Limited (FSP1011125) is an Authorised Body under Finsure New Zealand Limited's financial advice provider licence (FSP1005389). Disclosure statement
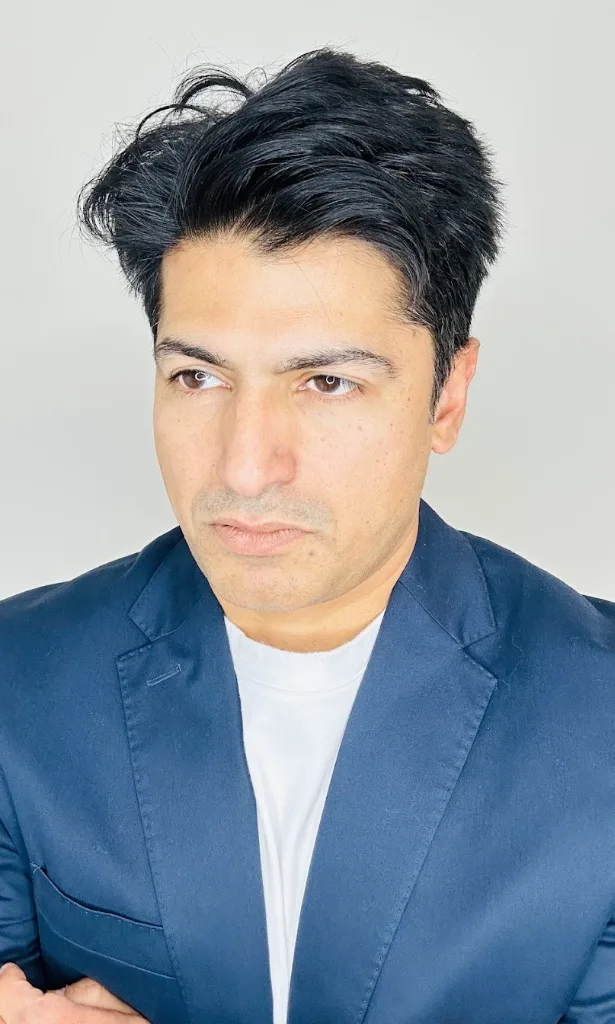
Your adviser
Mukhtar Kiyani
Director and Financial Adviser, with over 15 years of lending experience across ASB, Westpac and BNZ. Mukhtar works with Epsom clients by phone and video, from first call to settlement.